
Setting expectations for a successful swap
Doug Drabik discusses fixed income market conditions and offers insight for bond investors.
Elevated Treasury yields have created attractive income opportunities across the fixed income markets. Corporate and municipal bonds offer additional yield opportunities, while positively sloped yield curves provide investors with further motivations to extend maturities. For many investors, the opportunity to capture higher income and lock it in for longer periods has renewed interest in exploring bond swaps.
The motivation is understandable. Investors holding bonds purchased during a much lower interest rate environment may be eager to exchange those securities for bonds offering today's higher yields. However, a successful swap involves more than just replacing a lower-coupon bond with a higher-coupon bond. There are costs, consequences, and tradeoffs that must be considered. Higher prevailing interest rates alone do not automatically make a swap financially beneficial.
One of the most important considerations is understanding the yield of the bond being sold. Bond prices and yields move inversely. As market yields have risen, prices on many existing bonds have fallen. Although their coupons remain unchanged, their market prices have adjusted downward to provide yields competitive with newly issued bonds of comparable credit quality and maturity. In other words, a bond purchased years ago at a 2% yield may now offer a 5% yield to a new buyer at its current market price. This current market yield, sometimes referred to as the takeout yield, is the appropriate starting point when evaluating a replacement bond, not the yield at which the original bond was purchased.
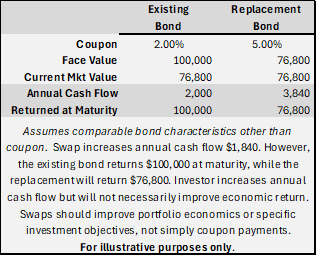
This helps explain why swapping into a bond with a similar maturity, credit quality, and structure is unlikely to produce a meaningful economic advantage. Bonds trade with a bid/ask spread: the difference between what a buyer is willing to pay and what a seller is asking to receive. Think about trading in a used car. The dealer will offer you a lower price than they can resell it for. Similarly, selling one bond and purchasing another introduces transaction costs. Exchanging two otherwise comparable securities generally offers little opportunity to overcome those costs.
A successful swap should accomplish something meaningful, and that benefit will usually involve a tradeoff. Consider an extension swap. When yield curves are steep and upward sloping, investors may capture additional income by exchanging shorter-maturity bonds for longer-maturity securities. The tradeoff is an extension of maturity and typically an increase in duration, making the portfolio more sensitive to changes in interest rates. For investors seeking long-term income and predictable cash flow, that tradeoff may be worthwhile. The ability to lock in attractive yields for additional years can support long term investment objectives while reducing exposure to near-term reinvestment risk.
Of course, income enhancement is only one reason to consider a swap. Investors may also seek to improve credit quality, generate liquidity, harvest tax losses, restructure cash flows, or better align portfolio maturities with future financial needs. Each objective carries its own costs and considerations.
Ultimately, the measure of a successful swap is not simply a higher coupon or yield, but whether the transaction improves the portfolio in a way that justifies its costs and tradeoffs. Understanding what is gained, what is surrendered, and how the exchange supports the investor's objectives is what makes a swap successful.
The author of this material is a Trader in the Fixed Income Department of Raymond James & Associates (RJA), and is not an Analyst. Any opinions expressed may differ from opinions expressed by other departments of RJA, including our Equity Research Department, and are subject to change without notice. The data and information contained herein was obtained from sources considered to be reliable, but RJA does not guarantee its accuracy and/or completeness. Neither the information nor any opinions expressed constitute a solicitation for the purchase or sale of any security referred to herein. This material may include analysis of sectors, securities and/or derivatives that RJA may have positions, long or short, held proprietarily. RJA or its affiliates may execute transactions which may not be consistent with the report’s conclusions. RJA may also have performed investment banking services for the issuers of such securities. Investors should discuss the risks inherent in bonds with their Raymond James Financial Advisor. Risks include, but are not limited to, changes in interest rates, liquidity, credit quality, volatility, and duration. Past performance is no assurance of future results.
Investment products are: not deposits, not FDIC/NCUA insured, not insured by any government agency, not bank guaranteed, subject to risk and may lose value.
To learn more about the risks and rewards of investing in fixed income, access the Financial Industry Regulatory Authority’s website at finra.org/investors/learn-to-invest/types-investments/bonds and the Municipal Securities Rulemaking Board’s (MSRB) Electronic Municipal Market Access System (EMMA) at emma.msrb.org.